
Underwritten on what the property actually earns — not what the seller's spreadsheet says it could.
Every investment property comes with two sets of numbers: what it earns, and what the seller says it could earn.
The gap between those is where returns are won and lost. A rent roll with three units at below-market rents and eighteen months left on the leases isn’t a problem — it’s the whole opportunity, if you priced it correctly. The same rent roll, bought at a stabilized cap rate, is just an overpay with extra steps.
We represent investors buying and selling income property across Madison and Dane County — duplexes through mid-size apartment buildings, net-leased retail, mixed-use, and small commercial portfolios. Acquisition and disposition both.
Tell us what you’re looking for or what you’re holding. (608) 445-2370.
The Threshold
There’s a hard break in multi-family, and it sits between four units and five.
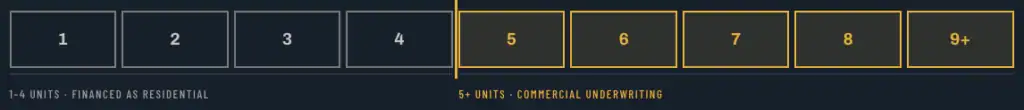
1–4 units
Conventional residential lending applies — longer amortization, lower down payment options, qualification based substantially on your personal income and credit, and rates that track the residential market. A duplex, triplex or fourplex is bought roughly the way a house is bought.
5+ units
Different lenders, different products, and underwriting that runs on the property's income rather than yours. Expect a larger down payment, a shorter loan term with a longer amortization and a balloon at the end, and a debt service coverage requirement the property itself has to satisfy.
A five-unit building priced barely above a four-unit can require substantially more capital and an entirely different financing conversation. If you’re building a portfolio, know which side of the line you’re on before you make offers — and know that crossing it deliberately, once you have the reserves, is how most Dane County investors scale.
Underwriting
Sellers lead with a pro forma. We start with a T-12 and work forward.
Twelve months of collected rent — not scheduled rent, and not market rent. Ask for bank statements if the numbers look tidy.
Current rent, lease expiration, tenant tenure, deposits held, and any concessions. Below-market rents are upside only if the leases turn over in a timeframe that works for you.
Tax bills, insurance quotes at your ownership rather than the seller's, utilities, management, turnover and maintenance history. Sellers routinely underestimate the last three.
Roof, mechanicals, parking lot and unit turns are real annual costs even when they don't appear on last year's statement. Underwrite them per unit per year.
Not the current occupancy — the vacancy this asset will run long term, given its unit mix and submarket.
Once the NOI is defensible, the cap rate tells you what to pay. Running it in the other direction — starting with the price and solving backward — is how people talk themselves into deals.
Properties near campus run on an academic calendar — leases signed far in advance, near-total turnover each summer, and a rent premium that comes with turnover costs and wear attached. Some investors build a whole strategy on it. Others avoid it entirely. Both are defensible; going in without knowing which you're doing isn't.
Epic, UW Health, the University, American Family and state government give Madison unusually stable rental demand for a metro this size. That's a genuine strength — and it's concentration risk worth being conscious of.
Security deposit handling, check-in procedures, notice requirements and disclosure obligations are regulated at the state level, and non-compliance carries real consequences. Moving from single-family into multi-family, the requirements scale with you.
Underwrite the tax line on what the property will be assessed at post-transaction, not what the current owner has been paying. The single most common underwriting error we see in Dane County.
Passive
A freestanding building with one tenant on a long-term NNN lease is the most passive commercial investment available. You’re primarily buying the tenant’s credit and the lease, not the building.
Tenant credit and whether the guarantee is corporate or franchisee, lease term remaining, rent escalations, and how much of the structure you're actually responsible for.
More than the name suggests. Some forms leave roof and structure with the landlord. Read the actual lease, not the marketing summary.
Minimal management, concentrated risk. When the lease ends or the tenant fails, you own a purpose-built building with one obvious use and a limited buyer pool.
If you’re selling an investment property and buying another, a 1031 exchange may let you defer the gain.
The deadlines are strict, they start at your closing, and they don’t move. You’ll need a qualified intermediary engaged before the sale closes — not after — and you should be identifying replacement property while your sale is still under contract, not once the clock has started.
We’re brokers, not tax advisors. Talk to your CPA early, because the structure has to be right before the first transaction closes. What we can do is line up the replacement side so you’re not identifying properties under pressure.
If you're buying multi-family in Dane County you'll either self-manage or hire a manager, and that decision affects your underwriting materially — management is a real line item, and self-management is a real job. We'll model both honestly, and we'll refer you to managers we'd use ourselves.What we do is the transaction: finding the asset, underwriting it, negotiating it, and selling it when the hold period is done.
Strategy
Lower risk
The property is performing at market — occupancy is normal, rents are current, deferred maintenance is minimal. You're buying a cash flow stream. Lower return, lower risk, less work.
Higher risk
Something is wrong that you can fix: below-market rents, deferred maintenance suppressing rents, poor management, or unused space. Higher return — and a project with real execution risk and a capital plan attached.
Most investors think they want value-add until they price the capital and the timeline. We'll be straight with you about which one a given building actually is — sellers routinely market stabilized assets as value-add because it sounds like upside.
Frequently Asked Questions
Cap rates vary by property type, asset quality, submarket and lease structure, and they move with the debt markets. Multi-family typically trades tighter than retail or office in this market. Rather than quote a number that’ll be stale, we’ll pull comparable Dane County transactions for the specific asset type you’re looking at.
Five. One to four units is financed under residential rules; five and above is commercial underwriting based on the property’s income, generally with a larger down payment and a shorter term with a balloon.
It has unusually stable demand for a metro this size — the University, UW Health, Epic, American Family and state government all anchor it. That stability is priced in, so yields are often tighter than in smaller Wisconsin markets. Whether that trade suits you depends on your strategy.
Actual is what the property collected. Pro forma is what the seller believes it could collect under different conditions. Buy on actual. Treat pro forma as a plan you’ll have to execute and fund yourself.
We handle the real estate side — the sale and the replacement acquisition, working to your identification and closing deadlines. The tax structure and the qualified intermediary come from your CPA and the QI. Bring us in early so the replacement search starts before the clock does.
Madison and all of Dane County — including Middleton, Sun Prairie, Fitchburg, Verona, Cottage Grove, Monona, DeForest, Waunakee, Oregon and Stoughton — plus investment transactions in surrounding Wisconsin counties.
Tell us your criteria — asset type, unit count, target return, hold period — or send us what you're holding and we'll tell you what it's worth today.